
Understanding How Missed Payments Affect Your Credit Score
💡 Key Takeaways
Learn how a single missed payment can influence your credit score, why payment history is crucial, and what steps you can take to mitigate the damage.
Key Takeaways
- Payment History is Paramount: It's the most significant factor in your credit score.
- Timing Matters: A payment reported 30 days or more past due will typically hurt your score.
- Duration and Frequency: The longer a payment is late and the more frequently it happens, the greater the negative impact.
- Impact Varies: Your current credit health influences how much a missed payment affects your score – those with excellent credit may see a larger drop.
- Steps to Take: Contact your lender immediately, pay any overdue amounts, and aim for consistent on-time payments going forward.
It can happen to anyone. Life gets busy, deadlines pile up, and suddenly, you realize you've missed a payment. While it might seem like a small oversight, a late payment on your credit report can have a more significant impact on your financial well-being than you might expect. This article will explain why consistent payments are so important and how even a single missed payment can influence your credit score.
The Importance of Payment History for Your Credit Score
Your credit score is a numerical representation of your creditworthiness – how likely you are to repay borrowed money. Lenders use this score to decide whether to approve you for loans, credit cards, or even rental agreements, and at what interest rates. One of the most critical factors that goes into calculating your credit score is your payment history.
Why Payment History is King
FICO says payment history accounts for about 35% of a FICO Score. This is because past behavior is generally seen as a good indicator of future behavior. If you have a consistent track record of paying your debts on time, lenders view you as a lower risk. Conversely, a history of missed or late payments suggests a higher risk, making lenders less likely to approve you or more likely to charge you higher interest rates if they do.
How a Missed Payment Impacts Your Credit Score
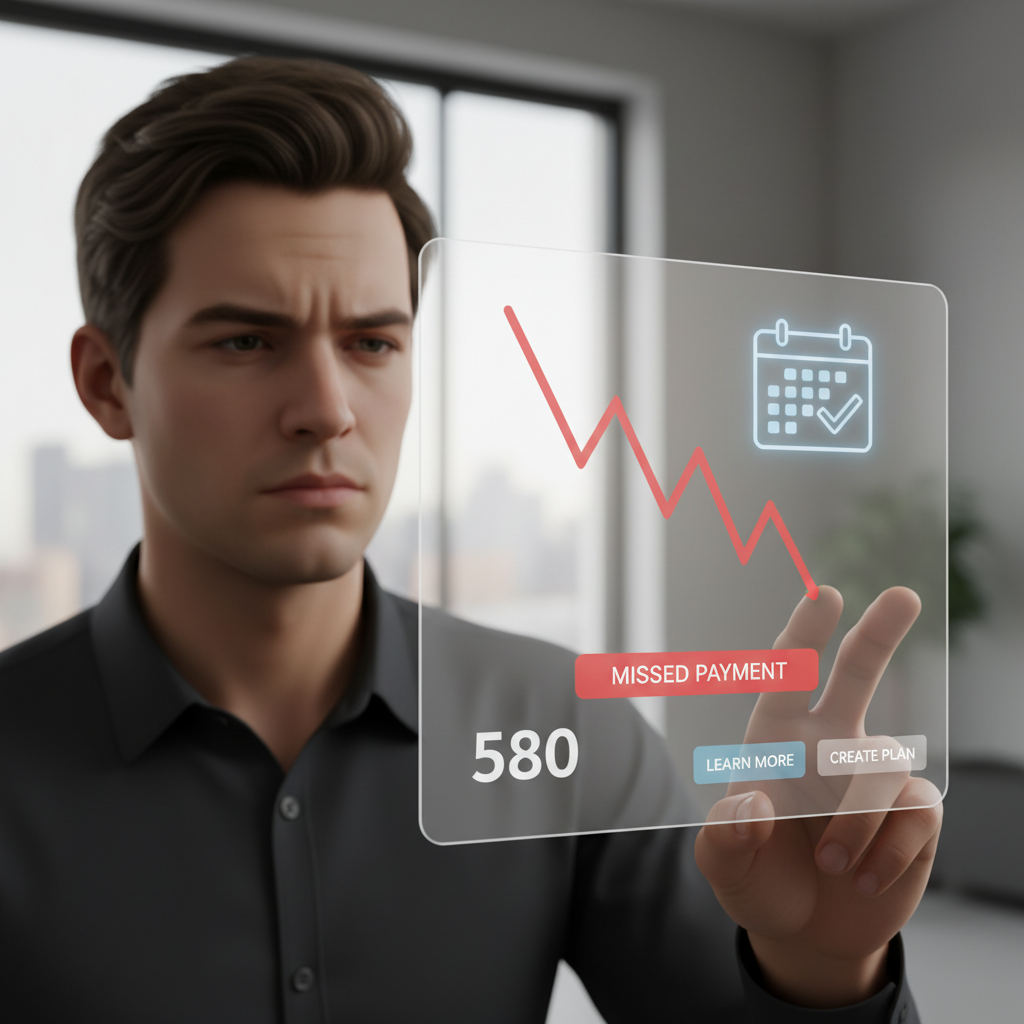
When you miss a payment, it doesn't immediately appear on your credit report. Lenders typically wait until the payment is 30 days or more past due before reporting it to the credit bureaus. Once reported, however, the impact can be considerable.
The 30, 60, 90+ Day Mark
- 30 Days Late: This is when a missed payment typically hits your credit report. Even a single instance can cause your score to drop. The exact amount depends on your overall credit profile – someone with an excellent score might see a larger initial drop than someone with an already lower score.
- 60 Days Late: If the payment remains unpaid for 60 days, the negative impact deepens. This indicates a more persistent issue, and the late mark on your report becomes more severe.
- 90+ Days Late: At 90 days or more, the damage is quite significant. This can lead to more drastic score drops and remains on your credit report for a longer period. Payments that go 120 or 180 days late can lead to accounts being charged off, which is a major negative mark.
Factors Affecting the Severity of the Impact
- Your Existing Credit Score: As mentioned, individuals with higher credit scores often experience a more significant drop from a missed payment because they have further to fall.
- How Long Ago It Happened: Recent late payments hurt your score more than older ones. While a late payment stays on your report for up to seven years, its influence diminishes over time.
- Frequency of Late Payments: A single missed payment will hurt, but a pattern of missed payments will cause much more sustained and severe damage.
- Type of Account: While all missed payments are bad, a missed mortgage payment might generally carry more weight than a missed retail store card payment, simply due to the typical size and importance of the debt.
Practical Steps After a Missed Payment
If you've realized you missed a payment, don't despair. There are steps you can take to minimize the damage and get back on track.
1. Contact Your Lender Immediately
As soon as you realize you've missed a payment, call your creditor. Explain your situation. They might be willing to waive the late fee or even agree not to report the late payment to credit bureaus, especially if this is your first offense and you have a good payment history importance with them. Be polite and proactive.
2. Pay the Overdue Amount As Soon As Possible
Even if it's already past the 30-day mark, paying the overdue amount immediately is crucial. This will prevent the payment from becoming 60 or 90 days late, which would cause even greater damage.
3. Set Up Payment Reminders
To avoid future missed payments, set up automatic payments, calendar reminders, or email alerts. Many banks and creditors offer these services to help you stay on track.
4. Review Your Credit Report
Regularly check your credit report from all three major credit bureaus (Equifax, Experian, TransUnion) to ensure the information is accurate. If you see a late payment that you believe is incorrect, dispute it with the credit bureau. Learn more about credit report basics.
5. Focus on Consistent On-Time Payments Going Forward
The best way to recover from a missed payment is to establish a long period of consistent, on-time payments. This demonstrates to lenders that the missed payment was an anomaly, and your score may gradually improve over time. Consider using our Credit Score Simulator to free credit score simulator (see how) different actions might impact your score over time.
The Long-Term Effect
A single missed payment can stay on your credit report for up to seven years. However, its impact on your score lessens over time, particularly after two years. By focusing on responsible credit habits, you can steadily rebuild your credit score and demonstrate your reliability to future lenders.
Ready to start improving your credit health? Begin your CredNudge journey today!
Frequently Asked Questions About Missed Payments
Q1: How long does a missed payment stay on my credit report?
A missed payment, once reported, can stay on your credit report for up to seven years from the date of the missed payment. However, its negative impact on your credit score generally diminishes over time, especially after the first two years.
Q2: Will a missed payment immediately lower my credit score?
Typically, a missed payment won't impact your credit score until it is reported to the credit bureaus as 30 days or more past due. If you make the payment before this 30-day mark, it's usually not reported as late and won't affect your score.
Q3: What's the difference between a late payment and a missed payment?
These terms are often used interchangeably. Generally, both refer to not making your payment by the due date. 'Missed payment' often implies you've entirely fumbled the payment, while 'late payment' simply means it wasn't on time. For credit report purposes, the key distinction is whether it's reported as '30 days late,' '60 days late,' etc.
Q4: Can I get a late payment removed from my credit report?
It's challenging but not impossible. If you have a strong history of on-time payments and this is an isolated incident, you can write a 'goodwill letter' to your creditor requesting they remove the late payment from your credit report as a courtesy. However, they are not obligated to do so. If the late payment is reported incorrectly, you can dispute it with the credit bureaus.
Q5: How can CredNudge help me improve my payment history?
CredNudge provides educational resources, tools like our Credit Score Simulator, and personalized insights to help you understand your credit report and make informed decisions. By understanding the impact of your actions, you can build a stronger payment history and improve your overall credit health. While CredNudge provides educational guidance only and cannot guarantee specific credit repair outcomes, our platform empowers you with the knowledge to make positive changes.
Disclaimer: CredNudge provides educational guidance only and does not offer financial or legal advice. We cannot guarantee specific credit repair outcomes or results. Always consult with a qualified financial advisor for personalized advice.
Sources
- FICO: What’s in your credit score
- FTC: Fixing your credit FAQs
Explore CredNudge Tools
Related Articles
Credit Utilization: The Complete Guide to the 30% Rule (and Why It's Wrong)
Credit utilization is 30% of your FICO score — but the "keep it under 30%" rule is oversimplified. Here's what the data actually shows.
Why Did My Credit Score Drop After Paying Off Debt?
Paid off a loan or credit card and your score dropped? Here's exactly why it happens — and what to do about it.
Does Credit 'Clear' After 7 Years? Understanding Credit Reporting Timelines
Many believe their credit magically 'clears' after seven years. We explain what genuinely happens with negative items on your credit report and how long they truly stay.
CredNudge provides educational guidance only. Credit outcomes vary by individual behavior. No guarantees.