
Does Credit 'Clear' After 7 Years? Understanding Credit Reporting Timelines
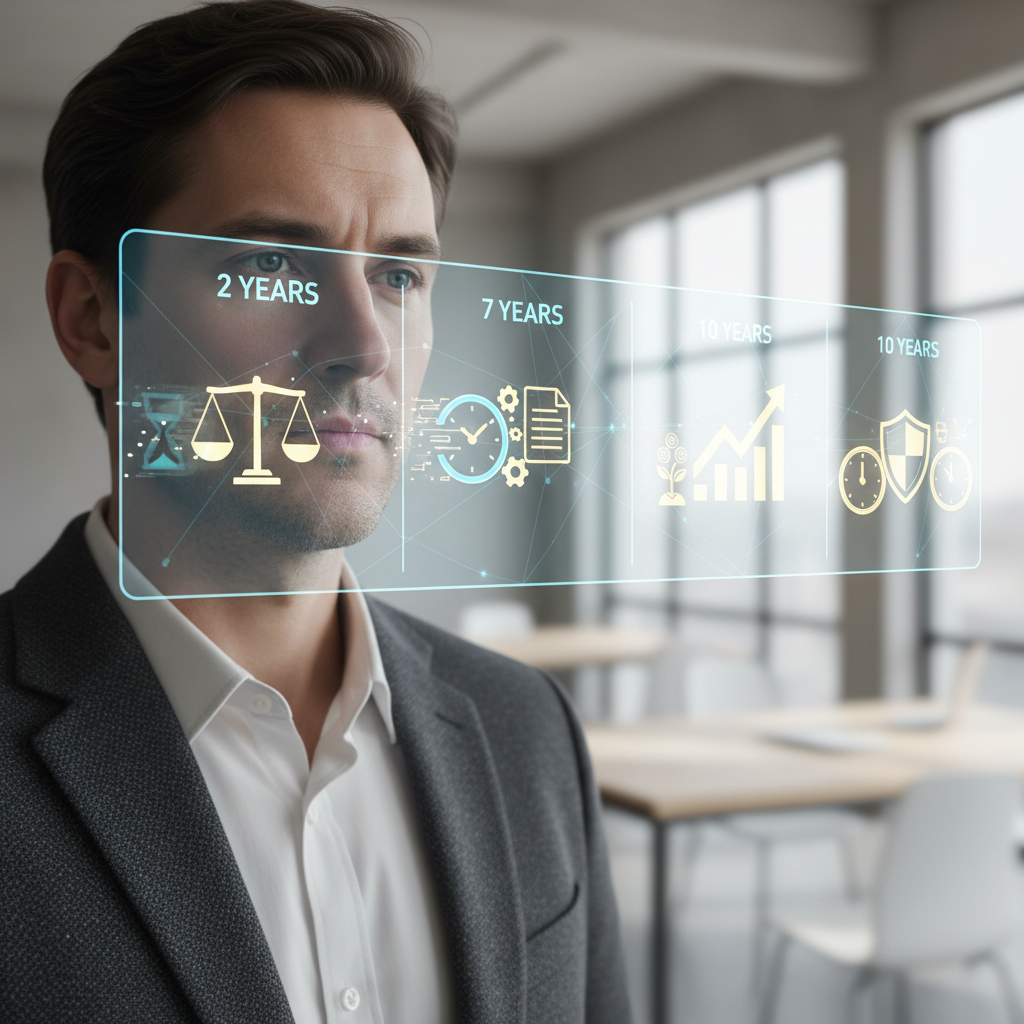
💡 Key Takeaways
Many believe their credit magically 'clears' after seven years. We explain what genuinely happens with negative items on your credit report and how long they truly stay.
Key Takeaways
- Most negative information, like late payments or charge-offs, typically falls off your credit report after 7 years.
- This *does not* mean your credit is 'clear' or that your debts disappear. Debts can still be owed and pursued.
- Bankruptcy reporting periods can extend beyond 7 years, up to 10 years for Chapter 7.
- Positive credit history, like on-time payments, can remain indefinitely and is beneficial.
- Understanding these timelines helps you manage your expectations and focus on building positive credit.
It's a common belief that after seven years, your credit report automatically 'clears' and suddenly looks brand new. While there's a grain of truth to this popular idea, it's also a significant misunderstanding that can lead to misinformed financial decisions. This article will break down what actually happens with your credit information over time, clarifying the 'seven-year rule' and its implications for your financial health.
The Myth vs. Reality: Does Credit Truly 'Clear'?
The phrase 'credit clears' suggests a complete wipe of all your financial history, both good and bad, after a certain period. This isn't accurate. What typically happens is that most *negative* information falls off your credit report after about seven years, as stipulated by consumer protection laws in many regions, such as the Fair Credit Reporting Act (FCRA) in the United States.
However, this doesn't mean your obligations vanish. A debt might no longer appear on your credit report, but you could still legally owe that money. Creditors might continue collection efforts, although in most places, there are statutes of limitations on how long they can sue you for a debt. Even if a debt is beyond the statute of limitations for legal action, the debt itself can still exist.
What Information Usually Stays on Your Credit Report for 7 Years?
Let's look at the types of negative items that typically have a 7-year reporting window:
- Late Payments: A single late payment or a series of them usually stay on your report for seven years from the date of the missed payment.
- Charge-Offs: When a creditor writes off a debt as unlikely to be collected. This also typically remains for seven years from the date of the charge-off.
- Collections: Accounts sent to collection agencies usually appear for seven years from the date of the original delinquency that led to the collection.
- Foreclosures: The records related to a foreclosure generally stay for seven years from the initial delinquency or the filing date, depending on the specific circumstances.
- Repossessions: Similar to foreclosures, these also typically remain for seven years.
- Civil Suits and Judgments: In some regions, these can stay for up to seven years or even longer, depending on local laws.
What Information Stays Longer or Shorter?
-
Bankruptcies: This is a major exception. Federal law allows any bankruptcy to be reported for up to 10 years, but the credit bureaus' general practice is to remove Chapter 13 bankruptcies (reorganization) after 7 years, per the CFPB.
-
Tax Liens: Depending on the type and whether they are paid, these can sometimes remain indefinitely or for extended periods beyond seven years in some jurisdictions, though recent changes in the US mean many no longer appear on credit reports. Always check local regulations.
-
Inquiries: When you apply for new credit, a 'hard inquiry' is placed on your report. These typically stay for two years, but their impact on your score usually diminishes much sooner.
-
Positive Information: This is the good news! Accounts like well-managed credit cards, loans paid on time, and other positive payment histories can remain on your credit report indefinitely. This is crucial for building a strong credit profile.
Practical Steps for Managing Your Credit Report
Understanding these timelines is just the first step. Here's what you can do:
1. Regularly Review Your Credit Reports
It's vital to check your credit reports from all major credit bureaus at least once a year. This allows you to:
- Identify any errors or outdated information.
- See exactly when negative items are expected to fall off.
- Monitor for any fraudulent activity.
In many countries, you are entitled to a free credit report annually. Utilize this resource!
2. Dispute Inaccurate Information
If you find an error on your credit report, dispute it immediately with the credit bureau and the creditor. Removing inaccurate negative items can positively impact your score.
3. Focus on Building Positive Credit History
While waiting for old negative items to fall off, actively work on building positive credit. This means:
- Paying all your bills on time, every time.
- Keeping credit card balances low (ideally under 30% of your credit limit).
- Having a mix of credit types (e.g., a credit card and an installment loan) if appropriate and manageable.
- Avoiding opening too many new credit accounts at once.
The more recent and positive your credit history, the less impact older negative items will have over time.
4. Understand the Statute of Limitations for Debts
While an item might drop off your credit report, the debt itself could still be legally collectible for a certain period, known as the statute of limitations. This varies by region and type of debt. If a debt collector contacts you about a very old debt, understand your rights and the statute of limitations in your area before making any payment or agreement.
5. Seek Educational Guidance, Not Guaranteed Solutions
Be wary of any service that promises to 'clear' your credit quickly or make negative items disappear before their legal reporting period is up. Legitimate credit repair involves disputing inaccuracies and building a new positive history, not magic tricks.
The 'seven-year rule' is less about a clean slate and more about the gradual rehabilitation of your credit profile. As negative items age and eventually fall off, and as you consistently demonstrate responsible financial behavior, your credit score may improve. It's a journey of consistent effort, not a sudden transformation.
To learn more about improving your credit health, start your credit journey with CredNudge today.
Frequently Asked Questions (FAQs)
Q1: If a negative item drops off my credit report, do I still owe the debt?
A: Yes, generally. The removal of an item from your credit report does not erase the debt itself. You could still legally owe the money, and creditors might continue collection attempts, though there are often statutes of limitations on how long they can sue you for the debt. Contact the original creditor or a legal professional for clarity on specific debts.
Q2: Can I get negative information removed from my credit report before 7 years?
A: Only if the information is inaccurate or verifiable. If a negative item is legitimate and accurate, credit bureaus are legally obligated to report it for the allowed time frame. You can dispute errors, but you cannot legally have accurate information removed prematurely.
Q3: Does the '7-year rule' apply globally?
A: Reporting periods for credit information can vary significantly by country and even by specific regulations within a country. While 7 years is a common duration for many negative items in places like the United States, other regions may have different rules (e.g., 6 years in the UK, 5 years in Australia for some items). It's crucial to check the specific credit reporting laws in your jurisdiction.
Q4: What's the difference between a soft inquiry and a hard inquiry?
A: A 'soft inquiry' (like checking your own credit report or pre-approved offers) does not affect your credit score and isn't typically visible to lenders. A 'hard inquiry' (when you apply for new credit, like a loan or credit card) can slightly lower your score for a short period and stays on your report for two years.
Q5: How can I find out when specific negative items will fall off my credit report?
A: You can find this information by obtaining copies of your credit reports from the major credit bureaus. Each negative listing should have a 'Date of First Delinquency' or similar date, from which the reporting period is typically calculated. If you're unsure, you can contact the credit bureau for clarification.
Disclaimer: CredNudge provides educational guidance and information only. We do not offer financial advice, nor do we guarantee specific credit repair outcomes. Individual financial situations vary, and it is recommended to consult with a qualified financial advisor for personalized advice.
Ready to understand and improve your credit? Explore our tools and resources:
- Start Your Credit Journey
- Use Our Credit Simulator
- Understand Our Plans
- Explore More Learning Resources
Want to explore illustrative estimates before you act? Try our free credit score simulator to explore illustrative, simplified estimates of common credit habits, not predictions of your actual score.
Sources
- FTC: Fixing your credit FAQs
- CFPB: How long negative information remains
- FICO: Credit checks and inquiries
- CFPB: How to dispute a credit report error
Explore CredNudge Tools
Related Articles
Credit Utilization: The Complete Guide to the 30% Rule (and Why It's Wrong)
Credit utilization is 30% of your FICO score — but the "keep it under 30%" rule is oversimplified. Here's what the data actually shows.
Why Did My Credit Score Drop After Paying Off Debt?
Paid off a loan or credit card and your score dropped? Here's exactly why it happens — and what to do about it.
How to Improve Your Credit Score in Australia (2026 Guide)
Australia switched to comprehensive credit reporting in 2018 — which means there are now more ways to build and improve your credit score than ever before.
CredNudge provides educational guidance only. Credit outcomes vary by individual behavior. No guarantees.